Vimal Kumar Ambat and the Reality of Scale
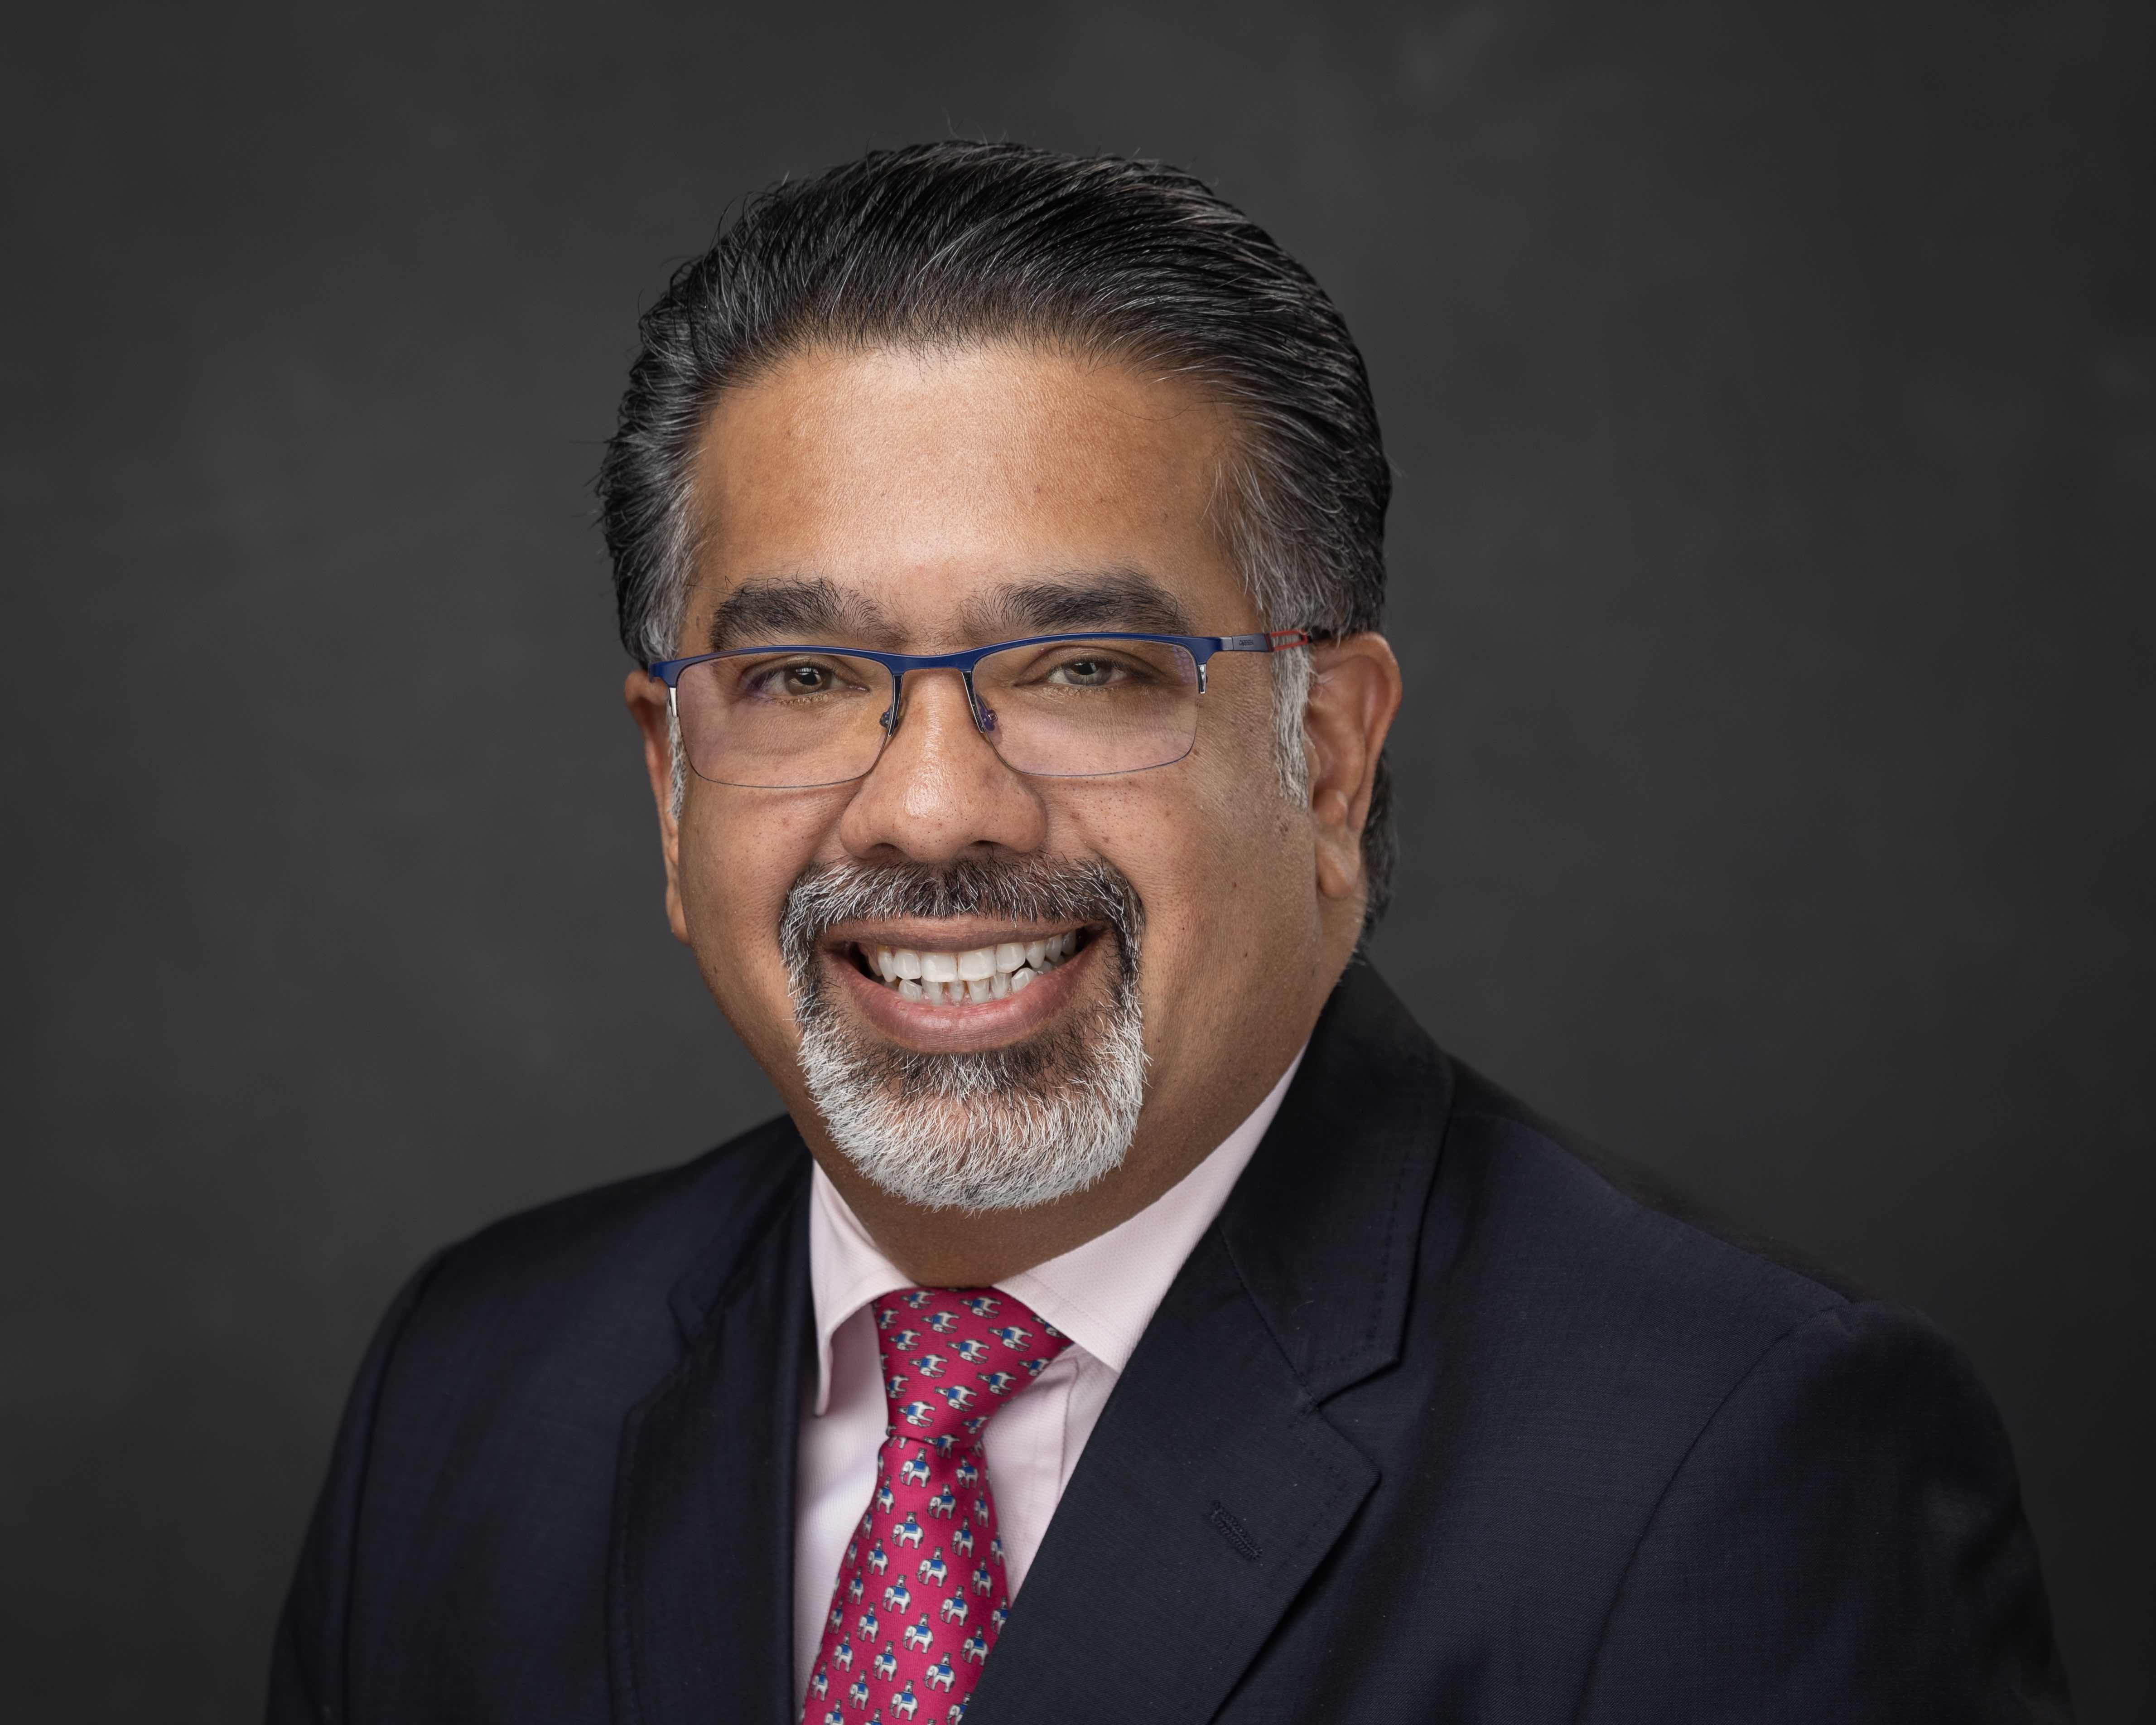
Few financial services leaders are shaped by experience across operating environments that demand such different forms of judgment. Banking disciplines decision-making through risk, credit, and an insistence on how money actually moves. Large-scale financial services test whether those disciplines hold under growth and geographic complexity. Fintech, by contrast, exposes every assumption to pressure, forcing innovation to coexist with regulation and trust. Moving across these systems is not incremental; it reshapes how leaders understand responsibility, scale, and consequence.
For Vimal Kumar Ambat, this progression has been steady and purpose-driven. His career spans traditional banking foundations, leadership of multi-country businesses where digital and payments reshape retail and SME finance, exposure to mass-market financial distribution through mobile money, and ultimately the task of building a regulated fintech from first principles. That trajectory brings a central question into focus - one that frames the discussion that follows: how do you build financial services that scale, once you know where scale goes wrong?
When Scale First Reveals What Systems Cannot Carry
Early exposure to traditional banking is formative in a specific way. It forces decisions to be argued in the language of risk, credit, and operational reality, where growth is never abstract and consequences surface quickly when controls are weak or incentives misaligned. In such environments, scale is measured not by momentum, but by the stability of what expands - portfolio quality, customer outcomes, and institutional accountability.
As responsibilities broadened into larger, multi-country portfolios, decision-making moved beyond functional execution into governance and P&L ownership. Performance became inseparable from the resilience of underlying systems, and scale revealed its first failure mode: it did not introduce new weaknesses so much as amplify existing ones - process gaps, inconsistent discipline, or infrastructures unable to absorb complexity without distortion. This transition marked a shift in how leadership judgment was formed for Vimal Kumar Ambat, moving scale from an abstract objective to a structural test.
Later experience operating within high-adoption financial services reinforced the same lesson from a different angle. When usage becomes habitual, reliability ceases to be a feature and becomes the product itself. Growth, at that stage, is not a commercial headline but sustained operational pressure. It is through this accumulation of constraint - banking discipline meeting real-world scale - that Ambat’s orientation toward building for durability takes shape, emphasising anticipation over reaction as systems are prepared to carry growth before it becomes visible to customers.
Scale, Distribution, and the Reality Behind Adoption
A defining chapter of Ambat’s career came through exposure to telco-led financial services and mobile money ecosystems. These models demonstrated how distribution, when aligned with clear value propositions, can embed financial services into everyday life at scale. They also revealed the fragility that accompanies rapid adoption when operational systems and governance lag behind usage.
Operating across diverse markets underscored a consistent insight: customers value reliability over sophistication. Simplicity at the interface conceals complexity beneath, and leaders who underestimate this complexity often encounter failures that are difficult to reverse. Distribution creates opportunity, but it also magnifies weakness.
This experience sharpened Ambat’s understanding of scale as an institutional challenge rather than a product one. Scaling financial services requires coordination across partners, operations, and controls. Without this alignment, growth introduces systemic risk. From a policy perspective, this reinforces the case for leadership that privileges system integrity over headline adoption metrics.
SMEs, Cash Flow, and Strategic Focus
Ambat’s transition into building a fintech business brought these accumulated lessons into sharper focus. Rather than pursuing broad feature expansion, the strategy centred on a specific and often overlooked constraint facing small and medium-sized enterprises: cash-flow predictability. While SMEs are widely recognised as economic engines, their most common failure mode is not lack of demand, but the inability to manage settlement delays and liquidity gaps.
This insight reframed the problem being addressed. Payments, in isolation, are rarely the core issue. The underlying challenge lies in how cash moves, settles, and becomes available for operational use. By designing around this reality, the emphasis shifts from transaction processing to financial infrastructure.
The strategic significance of this focus is twofold. First, it aligns product development with lived customer experience rather than abstract growth narratives. Second, it positions trust and reliability as central value drivers. For leadership, this reflects a broader principle: sustainable differentiation often emerges from addressing invisible constraints rather than visible trends.
Leadership as Repeatable Decision Quality
Across these phases, Ambat’s leadership philosophy has converged on a consistent theme: performance should not depend on individual heroics. In complex, regulated environments, resilience is built through systems that enable good decisions to repeat. This approach manifests in practices that separate execution speed from risk discipline, formalise decision rationale, and maintain short feedback loops.
Governance, in this framing, is not defensive. It is a strategic asset that allows organisations to move with confidence. Compliance and controls become enablers of scale rather than obstacles to it. This posture reflects an understanding that reputational capital, once lost, is difficult to recover.
The policy implication is clear. As financial services enters a more constrained phase, leadership advantage increasingly accrues to those who design organisations for durability. Judgment under constraint, rather than charisma or velocity, becomes the defining executive skill.
The evolution of financial services leadership reflects a broader shift in operating conditions. Growth remains essential, but it is no longer sufficient. The ability to balance innovation with reliability, and ambition with accountability, now defines long-term performance.
Vimal Kumar Ambat’s trajectory illustrates how such judgment is formed - through exposure to different systems of scale, risk, and responsibility. His positioning does not rest on rejecting change, but on sequencing it within structures that preserve trust. For the C-suite, the lesson is not personal, but institutional: leadership that treats durability as a strategic objective is better equipped to navigate the next phase of financial services evolution.